How to Get Insurance to Pay for Roof Replacement: A Process Guide
Learn how to document roof damage, review your policy, coordinate inspections, and communicate with your insurer without assuming replacement is covered.
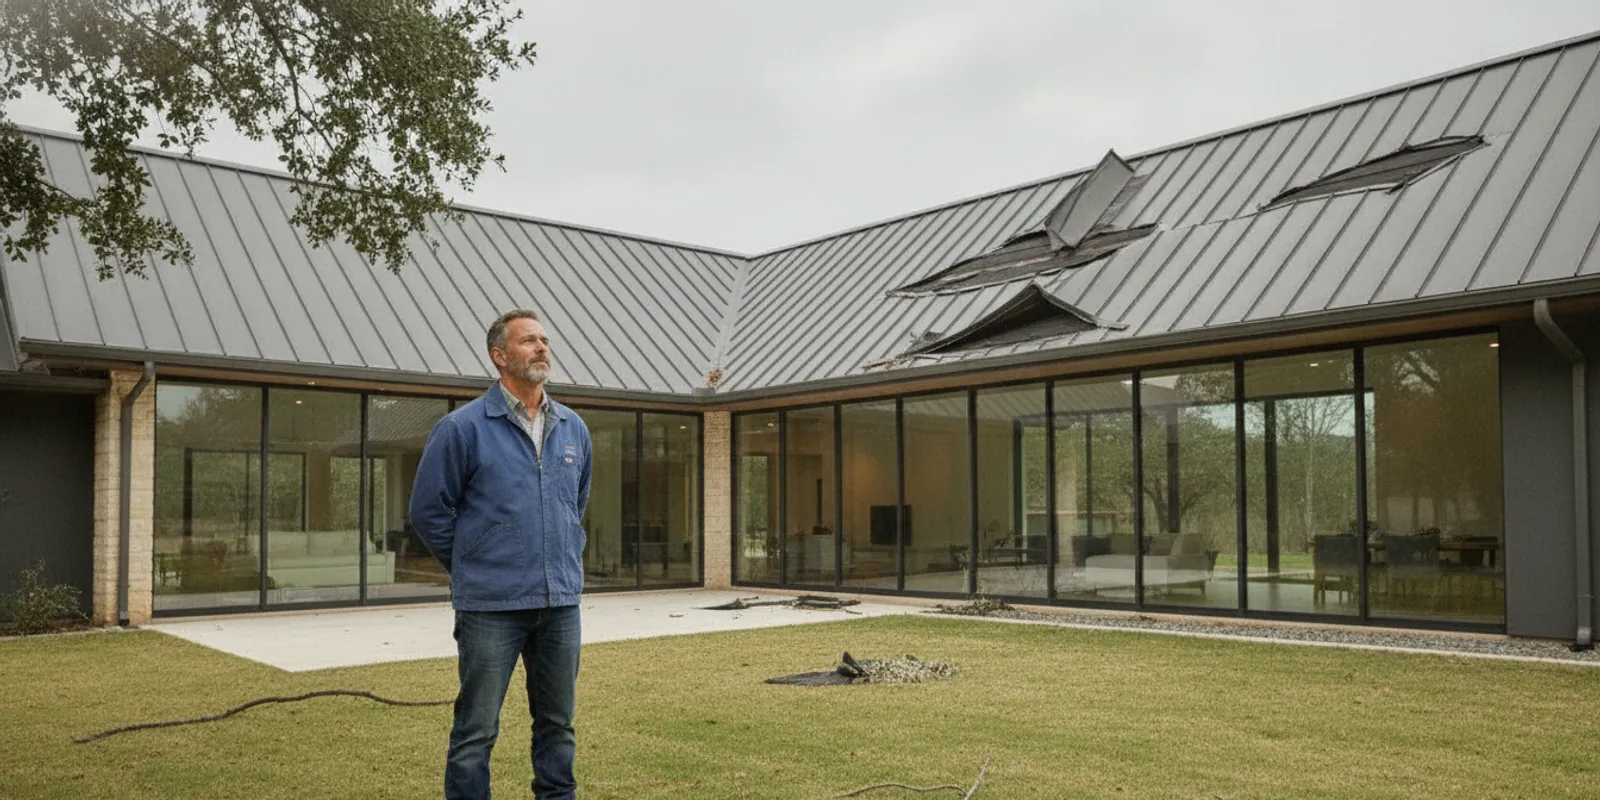
If you are wondering how to get insurance to pay for roof replacement, start by treating it as a documentation and policy-review process—not a guaranteed outcome. A roof problem may be covered, partly covered, or excluded depending on your policy, the cause and timing of the damage, and the insurer’s review. A careful record of what happened and what you observe can help you ask better questions and understand the next steps.
Contact One Real about your roofing questions
What does roof insurance usually evaluate?
A homeowners policy is a contract with specific terms, limits, conditions, and exclusions. There is no universal rule that a roof must be replaced whenever it leaks, looks worn, or has visible damage. The insurer evaluates the reported event and the policy language, then determines what it considers covered and what payment, if any, may apply.
Depending on the policy and circumstances, the review may distinguish sudden damage from ongoing deterioration or maintenance concerns. It may also consider the roof’s age and condition, the type and extent of damage, the reported date of loss, applicable deductibles, and how the policy calculates payment. Do not assume that a storm occurring near the time you noticed a leak proves the storm caused it.
For a general overview of the kinds of documentation and communication homeowners may encounter, the Colorado Roofing Association’s roofing insurance guide discusses the process. It is educational information, not a substitute for your own policy or advice from your insurer. Your policy and the insurer’s review control your particular situation.
What should you do first after noticing possible damage?
Put safety first. Look from the ground or another safe location, and do not climb onto a roof to inspect it. Storm-damaged surfaces can be slippery or unstable, and a view from the ground will not reveal every condition. If water is entering the home, protect people and belongings where it is safe to do so, and contact an appropriate professional for urgent property protection. Keep a record of any temporary steps you take and related receipts.
Make a brief timeline while details are fresh. Note when you first observed the issue, what prompted you to check the roof, whether there was a recent weather event, and where you noticed water or other effects inside. Separate what you personally observed from what someone else suggested. For example, “water stain appeared on the upstairs ceiling on Monday” is more useful than asserting a cause you have not confirmed.
- Photograph visible exterior conditions from safe ground-level positions, if possible.
- Photograph interior staining or other effects, and note the room and date.
- Save relevant messages, inspection notes, invoices, and temporary repair receipts.
- Write down the date and approximate time of a storm or other event if you know it.
- Avoid altering, discarding, or repairing damaged materials before you understand any documentation requirements, unless immediate action is needed to protect people or prevent further harm.
Photos are records of what was visible from a particular angle and date. They do not establish the cause of damage, the full condition of the roof, or whether a policy covers the repair. A professional roof inspection can add useful observations, but a contractor’s inspection is not the insurer’s coverage decision.
How can you review your policy before contacting the insurer?
Find the current policy documents, including the declarations page, endorsements, and any renewal documents that apply to the reported date. If you cannot locate them, ask the insurer or agent for the applicable documents. Reading the policy before a conversation can help you focus your questions, but you do not have to interpret complex wording on your own.
Look for the sections that describe covered property, covered causes of loss, exclusions, duties after a loss, deadlines or notice requirements, deductibles, and how a loss is valued. A roof-specific endorsement or limitation may change how the general policy language applies. Do not rely on a neighbor’s experience or a summary of a different policy; even policies from the same insurer can have different terms.
It can help to create a simple list of questions for your insurer:
- What policy and endorsements apply to the date I reported?
- What information should I provide, and how should I submit it?
- Are there time-sensitive notice, inspection, or documentation steps I should know about?
- What deductible or roof-specific terms may apply?
- How will the insurer explain its decision and any estimate or payment calculation?
- If the insurer identifies a difference between its estimate and a contractor’s estimate, what is the appropriate process for submitting supporting information?
Ask the insurer to point you to the relevant policy language when an answer is unclear. Keep a copy of the documents and notes from the conversation. An agent may be able to explain policy features, while the insurer handles the claim review; ask who is responsible for each question rather than assuming every representative can make a coverage decision.
When should you arrange a roof inspection?
An inspection can help you understand visible roof conditions and identify questions to raise. It can be useful before or after you contact the insurer, depending on the situation and the insurer’s instructions. If you have already reported a loss, ask whether the insurer wants to inspect before you schedule work beyond necessary temporary protection. Do not delay a required notice or safety measure while waiting for a contractor appointment.
Choose a qualified roofing professional to assess the roof and explain what was observed. Ask for clear documentation, such as dated photographs, a description of the areas reviewed, and a written estimate when appropriate. A useful report distinguishes observed conditions from conclusions about cause. If the professional cannot determine when or how a condition arose, the report should not present that uncertainty as certainty.
One Real Roofing and Construction describes residential and commercial roofing services in Texas, including the Dallas–Fort Worth area. The company also states that it offers a free roof inspection. A free inspection is an opportunity to discuss observed roofing conditions; it is not a promise that insurance will cover work, that the roof needs replacement, or that an appointment is available at a particular time. Review the roofing and construction services information or contact the company to discuss your project.
For more context on what a roof inspection may examine, see this roof inspection checklist. An inspection is not a substitute for a policy review, and it cannot by itself determine what the insurer will pay.
How should you prepare for an insurer’s inspection?
Follow the insurer’s directions about scheduling, access, and records. If you can be present, have your timeline, photos, policy questions, and any contractor observations available. You may also ask the insurer in advance whether it wants specific documents or whether another person should attend. Do not assume that an insurer’s inspection and a contractor’s inspection have the same purpose.
During the visit, take notes about what areas were inspected and what the representative said would happen next. Ask how and when you will receive findings or a written estimate, and how to provide additional information. If you have an independent roofing assessment, ask how to submit it. Keep the conversation factual: describe what you noticed and when, rather than insisting on a cause unless you have evidence to support it.
If the roof is unsafe to access or conditions change before the inspection, tell the insurer. Ask how to document the change and what temporary steps are appropriate. Keep receipts and photographs of temporary work where practical, and do not discard removed materials if the insurer has asked to see them. Follow professional safety guidance; preserving evidence does not require putting anyone at risk.
What records should you keep throughout the process?
Use one folder—digital or paper—for the claim and repair records. Organize it by date, and retain copies of anything you submit. Good recordkeeping reduces confusion when several people discuss the same roof at different stages.
- Event and discovery notes: dates, weather information you personally know, and when symptoms appeared.
- Photos and videos: keep original files when possible, with dates and brief descriptions of the location.
- Inspection records: reports, estimates, photographs, and the name or business of the person who prepared them.
- Insurer communications: claim reference, representative names, call dates, written instructions, and follow-up items.
- Property protection: temporary repair descriptions, receipts, and any documentation requested by the insurer.
- Repair documents: proposals, scope descriptions, invoices, permits or other records if applicable, and completion information.
After a phone call, consider sending a short written recap through the insurer’s stated channel. For instance: “On Tuesday, I spoke with your representative and understood that the inspection is scheduled for Friday and that I should send the dated photos through the portal.” Ask for correction if you misunderstood. Keep the tone neutral and specific. Avoid treating an informal comment as a final decision unless the insurer confirms it in writing.
How can you compare a roofing estimate with the insurer’s estimate?
Do not compare only the total amount at the bottom of two estimates. Review what each document says will be done, which roof areas and components are included, what quantities or measurements are used, and whether the scopes describe the same work. An estimate may use different assumptions from another estimate without either document answering the policy question.
Make a list of specific differences. Are accessories or related components included in one scope but not the other? Are quantities, material descriptions, or labor items different? Is a line item based on a condition that was not documented? Ask the roofing professional to explain the construction basis for its estimate and ask the insurer how it wants supporting information submitted. Keep questions tied to documented observations rather than simply asking one party to match another number.
Coverage, claim valuation, and construction scope are related but distinct. A contractor can describe the work it believes is needed and provide technical information. The insurer determines its position under the policy. If an estimate or decision is unclear, request an explanation and the applicable policy reference. Do not assume that an estimate is authorization to begin every proposed repair or that a contractor can decide the claim.
Before signing a roofing agreement, understand its scope, payment terms, responsibilities, and any conditions that apply. Ask how changes to the scope will be documented. Never agree to a plan based only on a verbal assurance that insurance will pay a particular amount. Confirm questions about coverage or payment directly with the insurer and obtain important agreements in writing.
What if the insurer’s decision or estimate does not answer your questions?
Start by identifying the exact point you do not understand. Is it the cause of damage, a policy exclusion, a measurement, an omitted item, a deductible, or a payment calculation? Request a written explanation and ask what additional records, if any, would be useful. If you have new photographs or a roofing assessment, provide them through the channel the insurer specifies and keep a copy.
Read any decision letter and the policy language it cites. Pay attention to any time limits or review options stated in the letter or policy. If you disagree, ask the insurer to explain its review or appeal process and how to submit additional information. You may also seek guidance from an appropriate consumer-protection resource or a qualified insurance professional. The right next step depends on the policy and facts; a roofing contractor cannot make that decision for you.
Maintain a complete account of submissions and responses. A clear record can help you explain what changed or what remains unresolved if the matter is reviewed again. Keep the discussion focused on evidence, the requested work, and the insurer’s stated process—not on a promised outcome.
What can a roofing company explain about the insurance process?
A roofing professional may inspect roof conditions, describe construction details, prepare an estimate, and explain technical differences between proposed scopes. Those are not the same as deciding whether an insurance policy covers a loss. The policyholder and insurer handle the insurance relationship, and the insurer makes its coverage determination under the applicable policy.
One Real Roofing and Construction describes offering an insurance-process consultation. A homeowner can use a conversation to ask general questions about organizing roofing documents or understanding a construction estimate. The company’s stated role should not be confused with legal advice, policy interpretation, claim filing on a policyholder’s behalf, or negotiating a settlement. No consultation can promise claim approval, a particular payment, or a full roof replacement.
When speaking with any contractor, ask who will prepare the estimate, what the inspection covers, and how information will be shared with you. You should receive and review your own documents. Be cautious about any person who tells you to misstate the cause or date of damage, guarantees an insurer’s decision, or asks you to sign a document you do not understand.
What common mistakes can complicate a roof claim?
Many avoidable problems come from acting on assumptions. Slow down long enough to distinguish what you know from what still needs to be checked.
- Assuming a storm caused every roof issue: record the timing and observations, then let the relevant inspections and policy review address cause.
- Climbing onto a damaged roof: do not risk injury to get closer photographs; use safe ground-level views and arrange a professional assessment.
- Waiting to ask about notice requirements: check your policy and contact the insurer promptly to learn its process and any applicable deadlines.
- Authorizing extensive work before clarifying inspection needs: address immediate safety and property-protection needs, but ask the insurer what it needs to inspect or document before non-urgent work.
- Assuming a contractor can guarantee coverage: a contractor can explain construction observations, not decide what a policy will pay.
- Failing to keep copies: save estimates, emails, photos, receipts, and the insurer’s written instructions.
- Signing blank or unclear paperwork: read agreements carefully, ask questions, and keep a signed copy.
- Treating the deductible as optional: review the policy and ask the insurer how it applies. Do not rely on promises to waive, rebate, or absorb a deductible.
How do you move from a claim decision to a roof project?
If the insurer issues a decision or estimate, read it carefully and compare it with your own records. Ask about any unexplained line items, payment timing, required documentation, or steps before work begins. The answer may depend on the policy and the insurer’s procedures. Do not treat a partial payment or an estimate as proof that all proposed replacement work is approved.
Before selecting a project scope, consider the roof’s observed condition, the insurer’s written position, and the work a roofing professional recommends. If there is a disagreement, resolve the questions you can before committing to a scope that may change. For a project-specific discussion, you can contact One Real Roofing and Construction. Its relationship-led model connects an independent sales consultant with company-managed construction; it does not change the insurer’s role or guarantee coverage.
For a broader look at roofing project planning, read the company’s guide to factors that shape a roof replacement estimate. Cost planning and insurance coverage are separate questions, so use the article to understand estimate factors rather than to predict a claim payment.
Discuss your roof project with One Real
Frequently asked questions
Does homeowners insurance always pay to replace an old roof?
No. Whether a policy covers roof work depends on its terms, the cause and timing of damage, the roof’s condition, and the insurer’s review. Age or a leak by itself does not establish coverage. Read the policy and ask the insurer how its provisions apply to your situation.
Should I call a roofer or my insurer first?
There is no single order for every situation. Prioritize safety and necessary temporary protection, review your policy’s notice instructions, and contact the insurer promptly to ask about its process and deadlines. A roofing inspection can help document conditions, but it does not replace insurer notice or determine coverage.
Can a roofing estimate make the insurer approve a replacement?
No. An estimate documents proposed work and cost assumptions; it does not control the insurer’s coverage decision. If estimates differ, identify the specific scope or measurement differences, ask the contractor to explain its technical basis, and ask the insurer how to submit supporting information.
Can a contractor file my claim or negotiate a settlement for me?
This guide does not offer that service or make a legal determination about who may perform particular insurance activities. One Real’s described consultation should be understood as roofing and insurance-process discussion, not a promise to file a claim, negotiate a settlement, or act as a public adjuster. Ask the insurer who should submit documents and seek qualified advice if you have questions about representation.
What if I am unsure whether the damage is storm-related?
Record when you noticed the condition and what you can safely observe. Ask a roofing professional to document the roof’s visible condition without presenting an uncertain cause as fact, and ask the insurer what information it needs. The insurer evaluates the claim under the policy and available evidence.
Organized records, careful questions, and a clear understanding of each party’s role can make a roof insurance review easier to follow. Coverage is never guaranteed by an inspection or estimate, so rely on your policy and the insurer’s written decision when planning the next step.